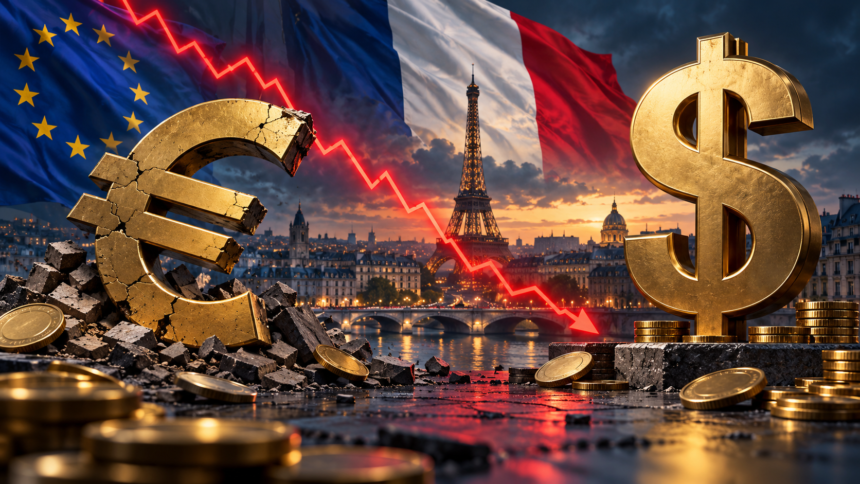
The euro fell to its lowest level against the US dollar in 17 months on Monday, as concerns over France’s budget deficit and a sell-off in government bonds raised fears of renewed debt-market instability in the eurozone.
The single currency touched $1.1161 during Asian trading, its weakest level since May 2025, before recovering some ground. The decline followed four consecutive weekly losses against the dollar, reflecting weakening confidence in the European currency.
France has become the focus of investor anxiety. High public debt and political divisions ahead of next year’s presidential election have raised doubts about the government’s ability to improve its finances. Investors are demanding a larger premium to hold French bonds rather than German debt, which is widely regarded as a safer European benchmark.
The gap between French and German government bond yields widened to around 150 basis points on Friday, reaching levels last seen during the eurozone sovereign debt crisis in 2011. The widening gap indicates greater concern about the risks associated with lending to France.
Political uncertainty in Spain added to the uneasy market backdrop after Prime Minister Pedro Sánchez announced an early election following the rejection of his government’s housing measures. French shares also underperformed: the CAC 40 fell around 1% on Monday even as other European stock markets advanced.
The dollar’s strength compounded the euro’s decline. Elevated US Treasury yields continued to support the American currency despite weaker-than-expected employment data, which reduced expectations of another Federal Reserve interest-rate increase this month.
The market moves have revived concerns that pressure on French debt could spread to other European economies. They reflect growing investor unease rather than confirmation that a new eurozone debt crisis has begun. Attention now centres on whether France can overcome political obstacles and restore confidence in its fiscal plans.